

Bain Capital related stories
All articles and analysis

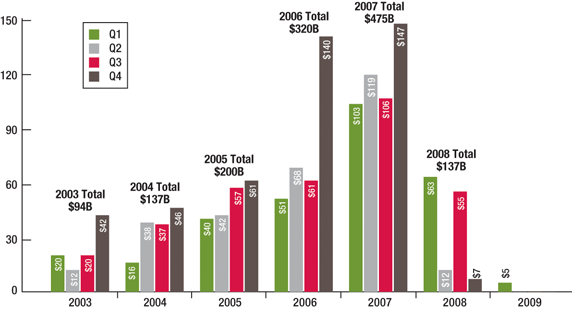 Add-Ons & Distressed Deals Punctuate A Slow Q1
The towering eleven-figure deals of yesteryear continued to shrink in the rearview mirror, as buyout pros treaded lightly in the first quarter in an effort to safely navigate the economic downturn.
- Weekly Downgrade Wrap-Up (Including Too Many Withdrawals)
As usual, we have a week’s worth of downgrades PE-backed company debt from Moody’s and Standard and Poor’s. (It’s a day early this week as tomorrow is a holiday.) This week there are only four, two of which were followed by withdrawals. As these withdrawals -- which happen “at the company’s request” -- increase, I'm starting to wonder about the ratings agencies (which naturally take their fair share of the blame for the credit crunch). I don’t like the idea that if a company doesn’t like what’s being said about its debt, it can make one phone call to silence the critics. It’d be like a public company dropping an analyst that rates it a “sell.” It’s unfair to debt holders.
- FleetCor Raises $100 Million
FleetCor, a Norcross, Ga.-based provider of branded fuel cards, has raised $100 million in Series E funding. The round was raised in conjunction with FleetCor's recent acquisition /36175/fleetcor-buys-clc-group/ of CLC Group Inc., a Wichita, Kansas-based provider of lodging management programs to businesses. Summit Partners led the round, and was joined by fellow return backers Advantage Capital and Advent International. New participants included Nautic Partners (prior owner of CLC), HarbourVest Partners and Performance Equity Management.
- Week in deals, April 6, 2009
Summary of tech companies and other businesses that raised financing in North America in the past week
- Weekly Downgrade Wrap-Up (13, Including A Rebellious S&P Rating)
As usual, we have a week of ratings downgrades on the debt of LBO-backed companies, via ratings agencies Moody’s and Standard & Poor’s. This week we have thirteen. One Note: This list excludes downgrades to ‘D’ for ‘default’ on companies that have filed for Chapter 11 bankruptcy protection. Check the quarterly LBO-backed bankruptcy list /35819/lbo-backed-bankruptcy-list-24-total-no-mega-busts-in-q1/ for those. However, it does include defaults and ‘SD,’ or ‘selective defaults’ on companies that have not yet filed for bankruptcy. I say this because this list is becoming just as much a way to track distressed debt exchanges as it is to track ratings downgrades. We also have a rebellious ratings agency first (at least in my experience). The story is this: Similar to public company analysts, debt-laden companies pay ratings agencies to examine and report on their debt. Sometimes, when a company’s ratings get too ugly, a company will ask the agency to withdraw its rating, and S&P or Moody’s will oblige. Such is the case with Six Flags, except instead of hiding its analysis from the public, S&P issued its first ever (to my knowledge) “unsolicited” rating on the company. Way to take on the man, S&P.
- Bain Markdowns Are Bad, But Not THAT Bad
Bain Capital joined the markdown parade this month, according to limited partners in the firm's past several buyout funds. It goes without saying that the numbers are ugly, but in context they're just homely. Or, if you like analogies: Bain Capital is to Terra Firma what Jerry Blank is The Wicked Witch of the West. Ok, moving on... The least ugly markdowns were for Bain Capital X, which is only around 25% invested. For the period ending Q4 2008, it was down approximately 10% quarter-over-quarter and 15% for the year. A bunch of companies in this portfolio are still being carried at cost, including Bright Horizons, Contec, Quintiles and The Weather Channel.
- peHUB Wire: Friday, April 3, 2009
Kleiner-Backed Terralliance Begins To Implode